
The Hidden Costs of Homeownership
Owning your homePart of the Coastal Blue mortgage guide
By Nick Atwal
2-Minute Summary
Closing costs in BC add 1.5–4% of the purchase price and must be budgeted upfront.
Strata fees, insurance, and utilities are recurring costs that many buyers underestimate.
Maintenance typically requires 1–2% of home value per year.
Renovation financing options (cash, HELOC, mortgage add-ons) all have trade-offs.
A monthly reserve fund cushions against surprises.
Your Path to Smarter Home Financing
One-Time Closing Costs in BC
Typical closing costs include:
- Legal & Notary Fees: $1,200–$2,500
- Appraisal & Inspection: $300–$700 each
- Property Transfer Tax: 1–3% of purchase price (unless exempt)
- GST on New Builds: 5% (first-time buyers can get it all back on new homes up to $1 million, with partial relief up to $1.5 million; other buyers may get a partial rebate under $450,000)
| Item | Estimated Cost |
|---|---|
| Legal & Title | $2,000 |
| Appraisal | $400 |
| Inspection | $500 |
| PTT (no exemption) | $13,000 |
| GST (if new build) | $37,500 |
Total: $15,900–$53,400
Nick's Note
I worked with a Burnaby buyer who didn’t budget for $18,000 in closing costs. Planning ahead avoided last-minute credit card debt.
Want me to estimate your closing costs? I can build a personalized breakdown for your price range and location.
Also Read: First-Time Buyer Incentives in Canada →
Recurring Costs Owners Underestimate
Strata/HOA Fees: $250–$800/month, and they usually rise each year.
Utilities: Hydro, water, gas, internet, often $300–$600/month combined.
Insurance: $1,200–$2,500 annually, higher for detached homes.
Nick's Note
One Surrey buyer had a perfect mortgage budget but forgot $450/month in strata fees. It stretched their finances until we restructured.
Also Read: Should I Buy Now or Wait for Rates to Drop? →
Maintenance & Repair Costs
Rule of thumb: 1–2% of property value per year for maintenance.
- $800,000 home = $8,000–$16,000/year.
- Older homes may require more for roofs, plumbing, or heating.
Nick's Note
A Vancouver couple faced a $12,000 roof repair two years in. Because they had a reserve fund, it didn’t derail their budget.
Want my one-page BC maintenance checklist? I can share it to help you plan season by season.
Also Read: How to Qualify for More (Without Stretching Too Far) →
Renovation & Upgrade Financing
Options to fund renovations:
- Cash Savings → No debt, but reduces reserves.
- HELOC (Home Equity Line of Credit) → Flexible, lower rates, but payments can rise with rates.
- Mortgage Improvement Add-On → Amortised into mortgage, but increases balance.
- Personal Loan/Credit Card → Fast access, but very costly.
| Option | Approx. Rate | Monthly Payment | Total Cost |
|---|---|---|---|
| Cash | 0% | $0 | $40,000 |
| HELOC | 7% | $233 (interest only) | $40,000+ |
| Mortgage Add-On | 5% | $233 (25yrs) | ~$69,800 |
| Personal Loan | 12% | $889 (5yrs) | ~$53,000 |
Nick's Note
A Langley client used a HELOC instead of a personal loan for a $25,000 renovation — saving thousands in interest.
Frequently Asked Questions
You Have Questions — We Have Answers!
Hidden Costs of Homeownership
How much should I budget for maintenance?
1–2% of property value annually.
Are strata fees optional?
No, they’re mandatory for condos and townhouses.
Can closing costs be added to my mortgage?
Typically no, they must be paid in cash.
Frequently Asked Questions
You Have Questions — We Have Answers!
First-Time Buyer Incentives
Can I combine FHSA and HBP?
Yes, most buyers can, which strengthens your down payment.
How much can the PTT exemption save me?
Up to $8,000, on homes priced up to $835,000 (a partial exemption up to $860,000).
Do incentives apply to both resale and new builds?
Yes, but new builds may also include GST.
Bottom Line
Owning a home in BC is rewarding, but only if you budget beyond your mortgage. Planning for all costs protects you from financial stress.
Quick Takeaways:
Closing costs =1.5–4% upfront.
Strata fees, utilities, andinsurance add recurring expenses.
Maintenance =1–2% annually.
Renovation financing has trade-offs.
Your Path to Smarter Home Financing
Written by: Nick Atwal
Mortgage Broker at Coastal Blue Mortgages
BCFSA licence 504576
Top 5% of Dominion Lending Centres brokers in Canada, 2022Canadian Mortgage Professional Rising Star, 2023
Nick Atwal is a mortgage broker at Coastal Blue Mortgages, helping families and business owners with complex structuring and refinancing solutions. Recognized as one of Canada’s rising young mortgage professionals by Canadian Mortgage Professional, he focuses on thoughtful planning, clear communication, and long-term financial outcomes.
More about NickStrata and HOA Fees in BC
Typical Ranges:
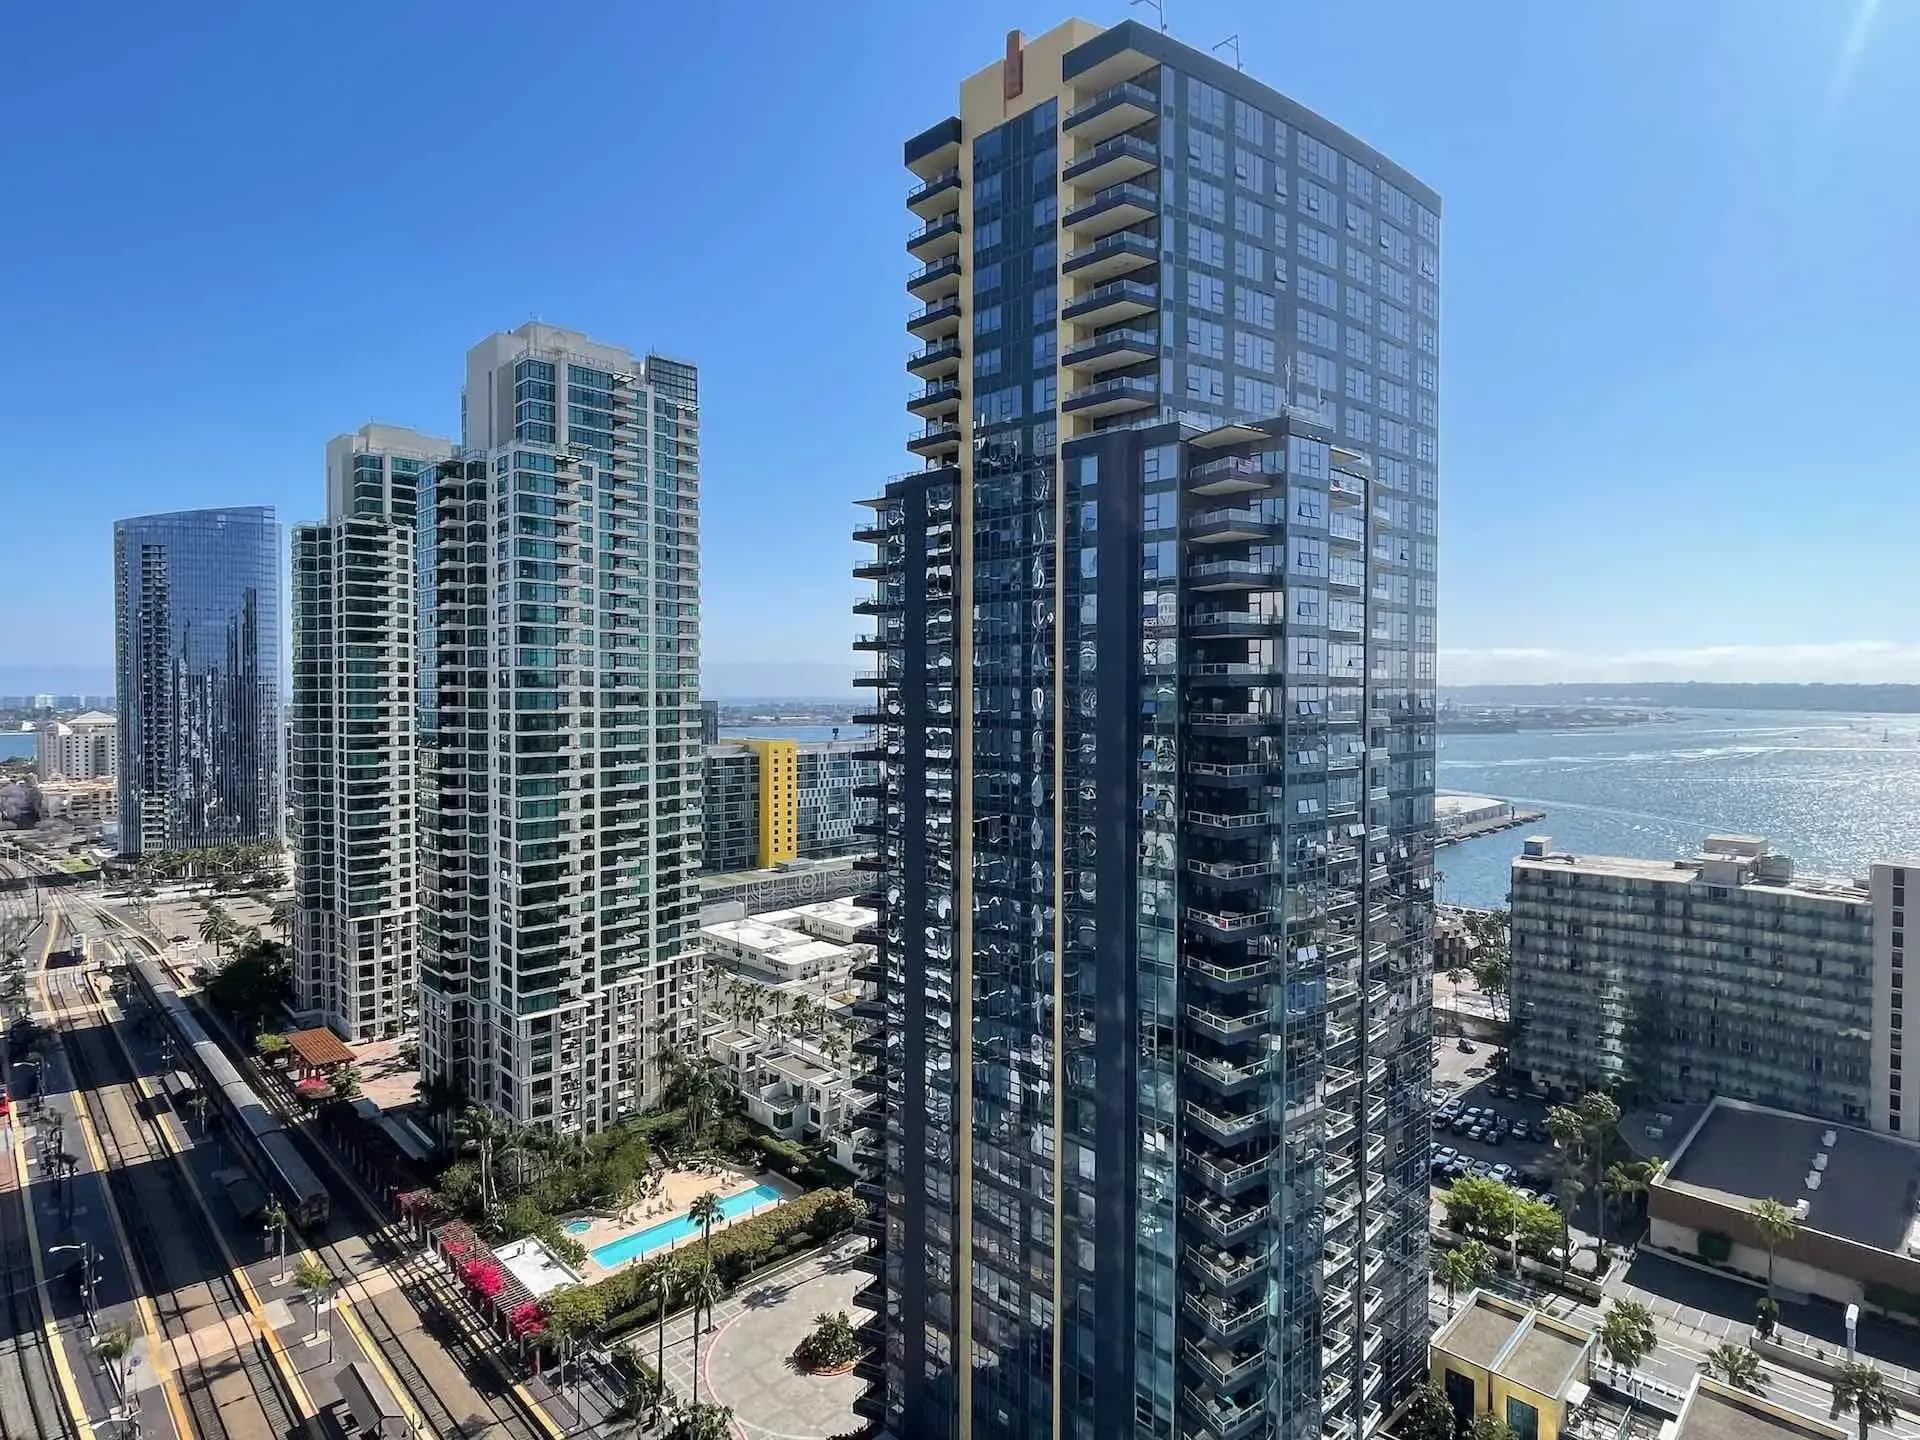
High-rise condos
often $400–$800+/month (elevators and amenities)
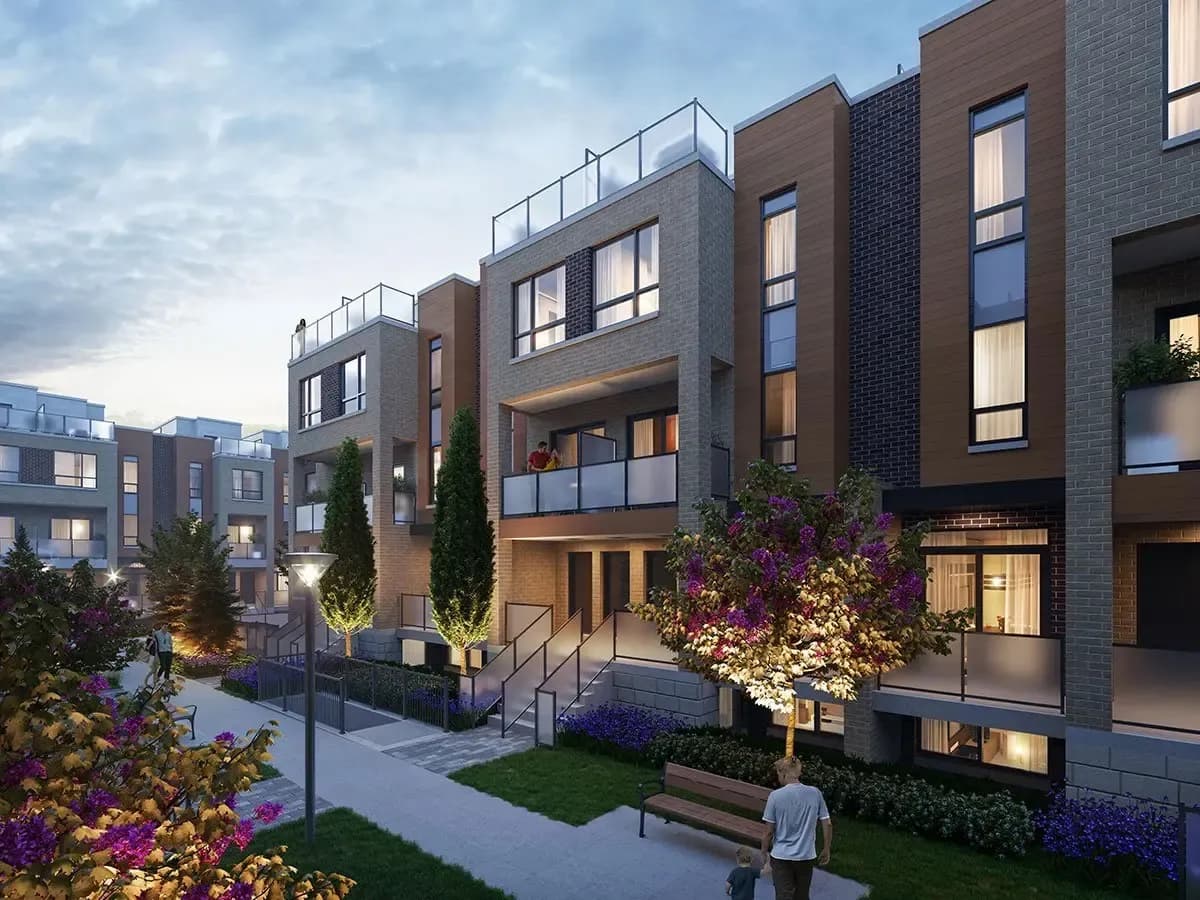
Low-rise condos
often $250–$500/month
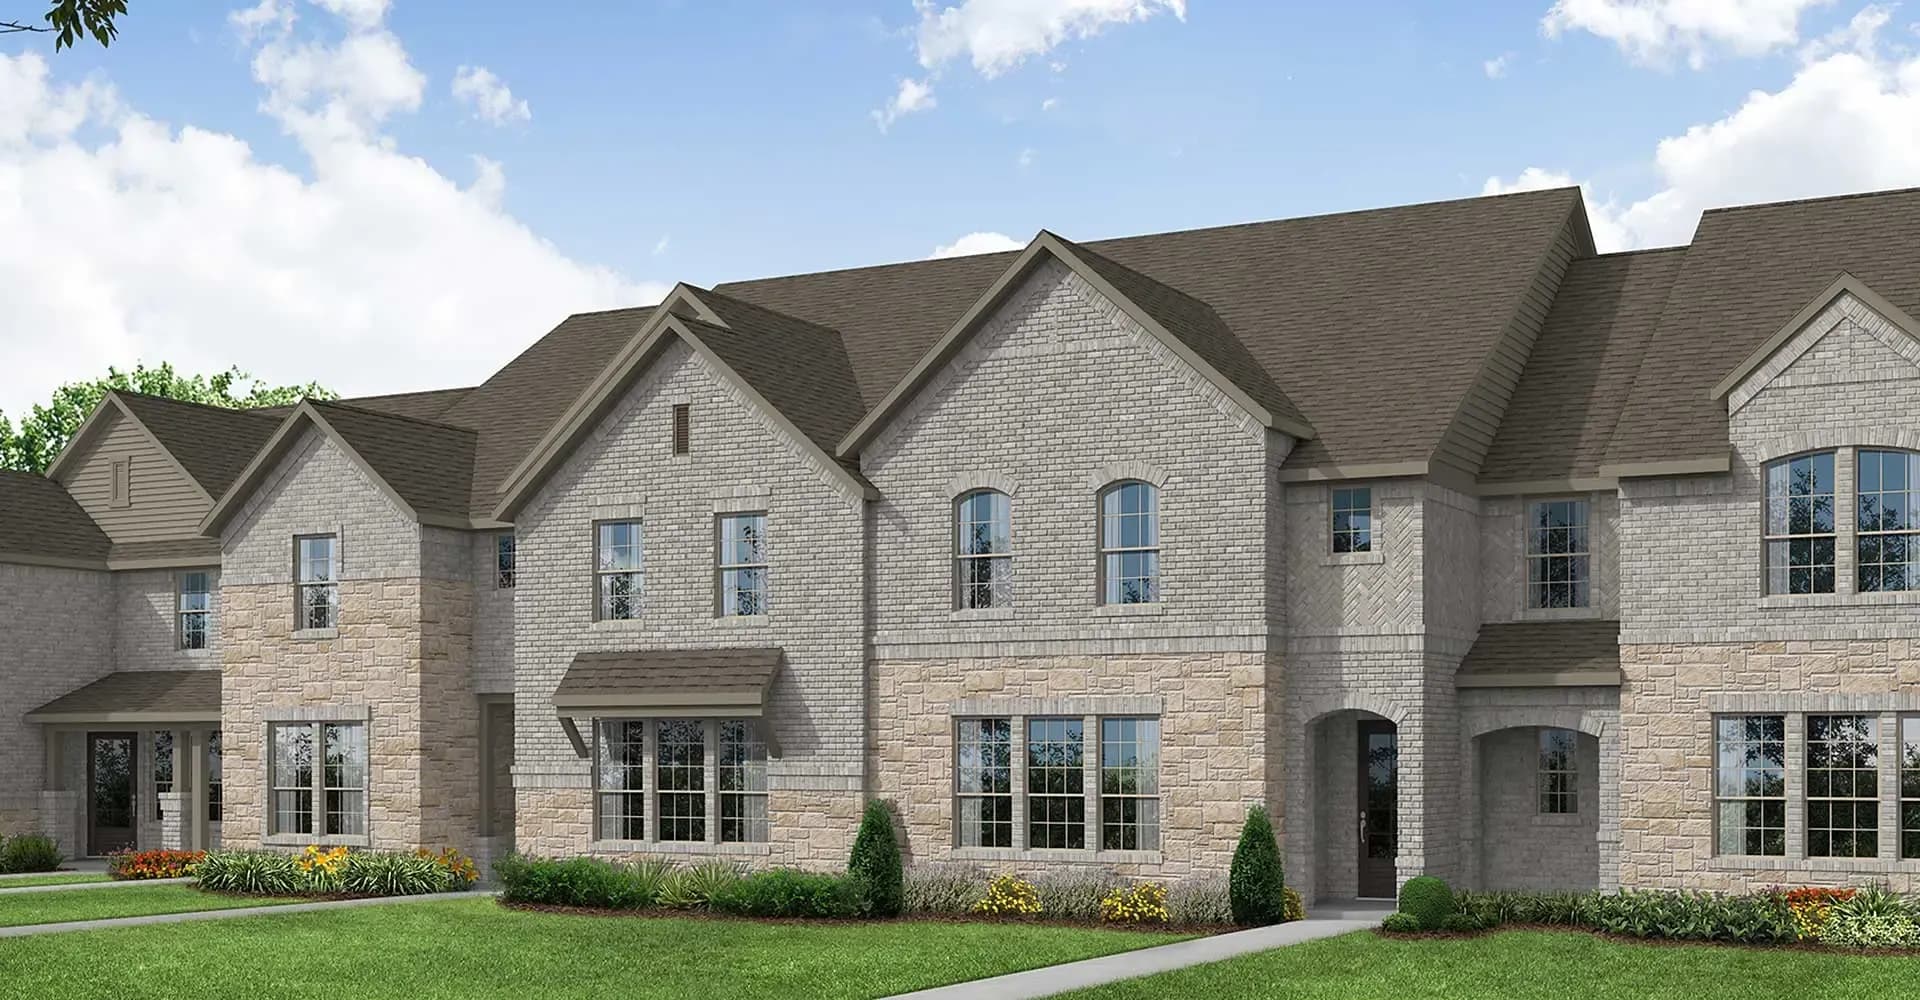
Townhouses
often $200–$500/month
Nick's Note
“A Vancouver condo buyer was surprised when their strata fee rose 15% after two years. We had built flexibility into their budget, so it was manageable.”
Frequently Asked Questions
Can strata fees decrease?
Rarely, most rise over time.
Do higher fees mean a bad building?
Not always — higher fees can mean proactive maintenance.
Quick Takeaways:
Expect $200–$800/month.
Fees rise with inflation and building age.
Budget for increases.
Home Maintenance Budgeting in BC
Rule: Budget 1–2% of property value annually.
Seasonal Checklist:
Spring
- Clean gutters
- Roof check
Summer:
- Exterior paint
- Landscaping
Fall
- Furnace tune-up
- Winterize plumbing
Winter
- Check drafts
- Monitor pipes
Nick's Note
A Kelowna client avoided a $10,000 plumbing repair because their fall inspection caught issues early.
Frequently Asked Questions
How much monthly should I set aside?
About $0.85–$1.65 a month for every $1,000 of home value (1–2% a year). On an $800,000 home, that’s about $665–$1,335 a month.
Do newer homes cost less?
Yes, but reserves are still important.
Quick Takeaways:
1–2% annually for upkeep.
Seasonal planning prevents costly surprises.
Keep a dedicated maintenance reserve fund.
Renovation Financing Options in BC
Financing options:
- Cash = cheapest, but reduces savings.
- HELOC = flexible, lower rates.
- Mortgage Add-On = spreads cost, but higher balance.
- Personal Loan/Credit Card = quick, but costly.
| Cash | HELOC | Mortgage add-on: |
|---|---|---|
| $20k out of pocket | ~$117/month interest (at 7%) | ~$116/month (25 yrs at 5%) |
Nick's Note
“A Surrey homeowner financed a $20,000 suite upgrade with a HELOC. The rental income covered the payments and boosted future resale value.”
Frequently Asked Questions
Can I add renovation costs to my mortgage?
Yes, some lenders offer purchase-plus-improvements programs.
Is a HELOC better than a personal loan?
Usually — rates are lower and repayment is flexible.
Quick Takeaways:
Cash = no debt, but drains reserves.
HELOC = best for flexibility.
Mortgage add-on = good if buying/renewing.
Personal loan = last resort.