
Private mortgages · British Columbia
Private mortgage lending in BC, funded fast
Nobody plans to need a private mortgage. When the bank says no, or not yet, one secured by your property can close the gap, and we map out your way back to a regular mortgage before you sign.
- Your way back to a regular mortgage, planned before you sign
- Loans from $25,000 to $5 million+, first or second mortgages
- Approval based on your equity and your plan, not just your credit score
- Funding in as little as 24 hours*
Licensed by BCFSA · Licence 504576 · ★ 5-star Google rating
- Loan sizes
- $25K–$5M+
- To fund, once your file is complete*
- 24 hrs
- Mortgages on BC property
- 1st & 2nd
- Mapped out before you sign
- Exit plan
The difference
A plan to get out, before you get in
Most people come to private lending when they're out of options. What makes it work is knowing from day one how you'll get back to a regular lender, and what has to happen first. So that's where we start.
“Nobody wants to go private. But when it's necessary, getting ahead of it with a proper plan means you can see the light at the end of the tunnel, and it helps you in the long run.”
Before you sign
We agree on where you're headed and what has to happen to get there: rebuilding credit, a tax return, a sale, a finished build. You see the plan alongside the full cost.
During the term
We check in along the way, so payments, credit and paperwork stay on track and nothing catches you off guard.
Before the term ends
A few months out, we line up the next lender, a bank, credit union or alternative lender, so you move on instead of renewing privately.
Back to regular lending
You're on a regular mortgage again, with the private loan behind you.
Who it's for
When a private mortgage makes sense
Bridge financing
Buying before your sale closes, or your new home closes before the money from the old one arrives. A short private loan covers the gap.
The way out:Paid out from the sale of your property.
Self-employed income
New business, big write-offs or income the bank won't count yet. Private lenders look at your equity while you build the track record a bank wants.
The way out:Refinance with a bank or alternative lender once your next tax return shows the income.
Construction and renovation
Fund a build, finish a project the bank won't touch mid-way, or renovate before you refinance at the new value.
The way out:Refinance with a regular lender at the finished value.
Debt consolidation
Roll high-interest cards, loans or tax arrears into one payment secured by your property, while you get back on track.
The way out:Refinance with a regular lender once your credit and debt load have recovered.
A way out of a tough spot
Missed payments, a consumer proposal, property tax or mortgage arrears. A private mortgage can buy time until a better lender will say yes.
The way out:A few months of on-time payments and a cleaner credit report, then back to an alternative lender or a bank.
Deadlines the bank can't meet
A closing date that won't move, a subject removal coming up, or a lender that needs more time than you have.
The way out:Moved to the regular lender as soon as it's ready to fund.
How it works
From first call to funds
Tell us what you need
Send the short form, call Nick, or start the full application. It takes a few minutes.
Plan the way out
Before anything else, we work out how you'll get back to a regular lender, and whether a bank or alternative lender could help instead.
Appraisal and written terms
We order the appraisal, take your file to the private lenders that fit, and you see the rate, every fee and the term in writing before you commit.
Funded
Your lawyer or notary registers the mortgage and the funds are released, in as little as 24 hours once the application, appraisal and legal documents are complete.
What private lenders look at and what you need
What private lenders look at
- The equity in your property
- The property itself: its type, location and condition
- Your exit plan: how the loan gets paid out
- That you can carry the payments for the term
What you'll need
- Photo ID
- Your latest mortgage statement and property tax notice
- An appraisal (we order it for you)
- What the money is for, and your plan to pay it out
- Proof of income, if you have it (not always required)
No surprises
What it costs
Private mortgages cost more than bank mortgages, and they work best as a short-term step. Each lender prices the loan after reviewing the property, the equity and your plan, so we don't publish rates. Expect a lender fee and a broker fee, plus the appraisal and legal costs.
You see the rate, every fee, the term and the payout rules in writing before you commit, next to your exit plan, so you know what the loan costs and when it ends. Every month you're back with a regular lender sooner is a month you're not paying private rates.
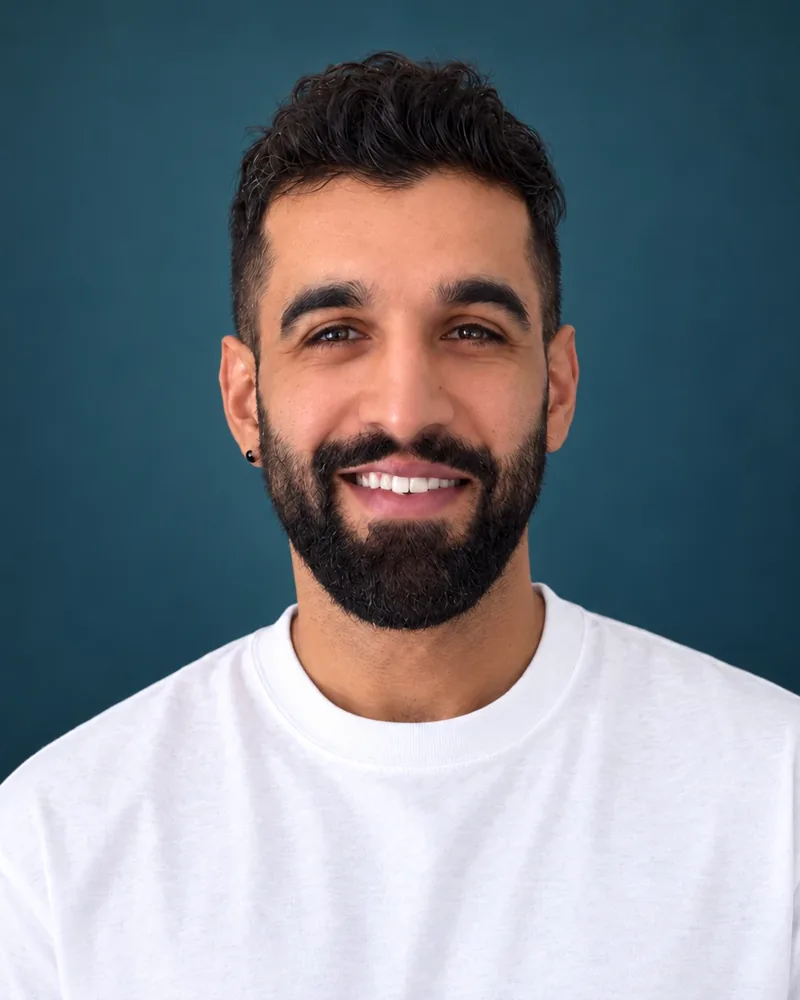
Work with Nick directly
Licensed mortgage broker in BC, with access to private lenders and mortgage investment corporations through the Dominion Lending Centres network, alongside 50+ banks, credit unions and alternative lenders.
Top 5% of Dominion Lending Centres brokers in Canada, 2022Canadian Mortgage Professional Rising Star, 2023
Frequently asked questions
You have questions — we have answers!
Private mortgages in BC
How fast can a private mortgage fund?
Often in as little as 24 hours once everything is in place: a completed application, an appraisal of the property, the lender's approval and the legal documents. The appraisal is usually what takes longest, so we order it as soon as you're ready to go. Tell us your deadline when you first call, whether it's a closing date, a subject removal or an arrears notice, and we'll plan the file around it.
How do I get back to a regular lender?
With a plan made before you sign. We work out what led to the private mortgage and what has to change: that may mean paying down debts and rebuilding your credit with on-time payments, filing another year of tax returns to show your income, finishing a renovation or selling a property. We set a target date when you sign, review your progress a few months before the term ends, and move you to an alternative lender or a bank as soon as one will approve you. If you need more time, renewing privately is possible, at a cost.
How much can I borrow with a private mortgage?
Private loans start at about $25,000 and go to $5 million or more. Private lenders often lend up to about 75% of the property's value, including any existing mortgage, though it varies by lender, property and location. They focus on your equity and the property more than your income, so a home with plenty of equity in an established area has more options. Rural, unusual or hard-to-sell properties usually get a lower limit.
What does a private mortgage cost?
More than a bank mortgage. Each lender sets the rate after reviewing the property, your equity and your plan, and payments are often interest-only. There is usually a lender fee and a broker fee, often set as a share of the loan, plus legal costs and an appraisal. Some lenders also charge to renew or to pay the loan off early. You get every cost in writing before you commit, so you can compare it with your other options.
Do I need good credit or proof of income?
Not the way a bank does. Private lenders lend mainly on your equity, so bruised credit, a consumer proposal, a new business or income that's hard to document doesn't rule you out. They still want to see that you can carry the payments for the term, or that the loan will be paid out by a sale or a refinance, so tell us the full picture up front. We also check whether a bank, credit union or alternative lender can help first.
Can I get a second mortgage instead of refinancing?
Yes. A second mortgage sits behind your existing mortgage, so you can access equity without breaking your first mortgage and paying a penalty. That can make sense when your first mortgage has a low rate or a large penalty. Rates and fees are higher than on a first mortgage, so we compare it with a refinance or home equity line and show you the total cost both ways.
Need funds soon? Let's talk today.
Call 778-838-8005, send the short form, or start the full application now.
*Funding in as little as 24 hours applies once the application, appraisal and legal documents are complete and the lender's conditions are met. All loans are subject to lender approval. Rates, fees and terms vary by lender and are disclosed in writing before you commit. Loans are secured by property in British Columbia.